Profit & Loss, Balance Sheet and Trial Balance
Three statements of your accounts, under Books ▸ Reports:
- Profit & Loss: did the business make money in a period?
- Balance Sheet: what does the business own and owe on a date?
- Trial Balance: does every ledger add up, debits against credits?
Each one is for one outlet, the one named at the top of the screen. The yearly income tax figures for all your outlets together are on ITR figures.
Why it matters for filing
Income tax. Profit is what income tax is charged on. If you file ITR-3 (full books), the return asks for your Profit & Loss and Balance Sheet under its own headings. If you file ITR-4, ITR figures uses the same figures for its financial particulars.
GST. These statements are not GST returns. GST returns are on the GST tab.
The bar at the top
| Control | What it does |
|---|---|
| Period | This month, this quarter, the financial year (1 April to 31 March), or your own dates. Financial year is the default. |
| Compare with | Adds a second column: the previous period, or the same period last year. |
| Show | Summary shows groups; Every ledger shows each ledger under its group. |
| Download PDF / Download Excel | A copy of the statement on screen, for you or your CA. |
Select any ledger name to open its entries in Accounts ▸ Ledger, for the same dates.
Profit & Loss
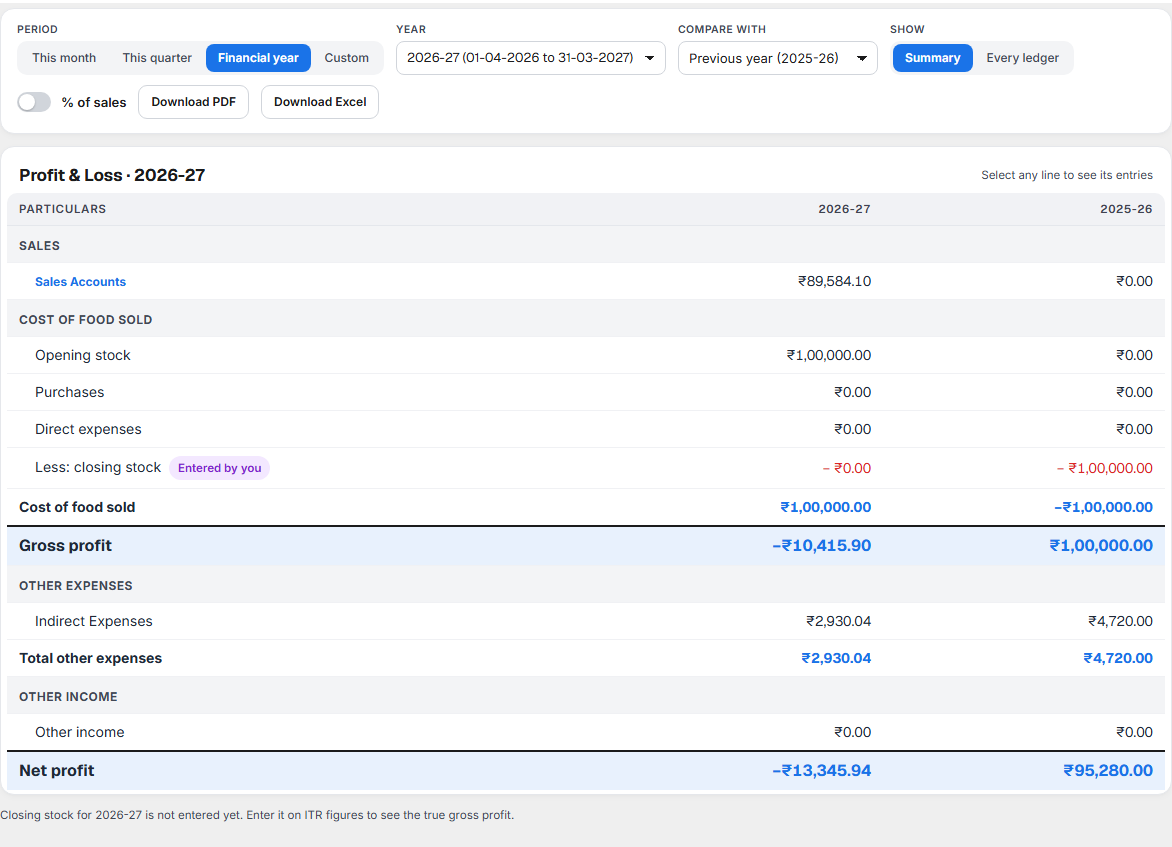
Read it from top to bottom:
| Line | What it means |
|---|---|
| Sales | Sales after discounts, before GST. |
| Cost of food sold | Opening stock + purchases + direct expenses (such as gas) − closing stock. |
| Gross profit | Sales − cost of food sold. What the food earns before rent and salaries. |
| Other expenses | Salaries, rent, power, repairs and the other expenses. |
| Other income | Income that is not from sales. |
| Net profit | Gross profit − other expenses + other income. A minus means a loss. |
% of sales shows each line as a share of sales, for example how much of every ₹100 sold goes on food.
Closing stock is the value of stock you entered for 31 March on ITR figures, marked Entered by you. It counts only for a whole financial year. For a month or a quarter there is no closing stock, so gross profit there is sales less purchases, and the note under the statement says so. Last year's closing stock is this year's opening stock.
Balance Sheet
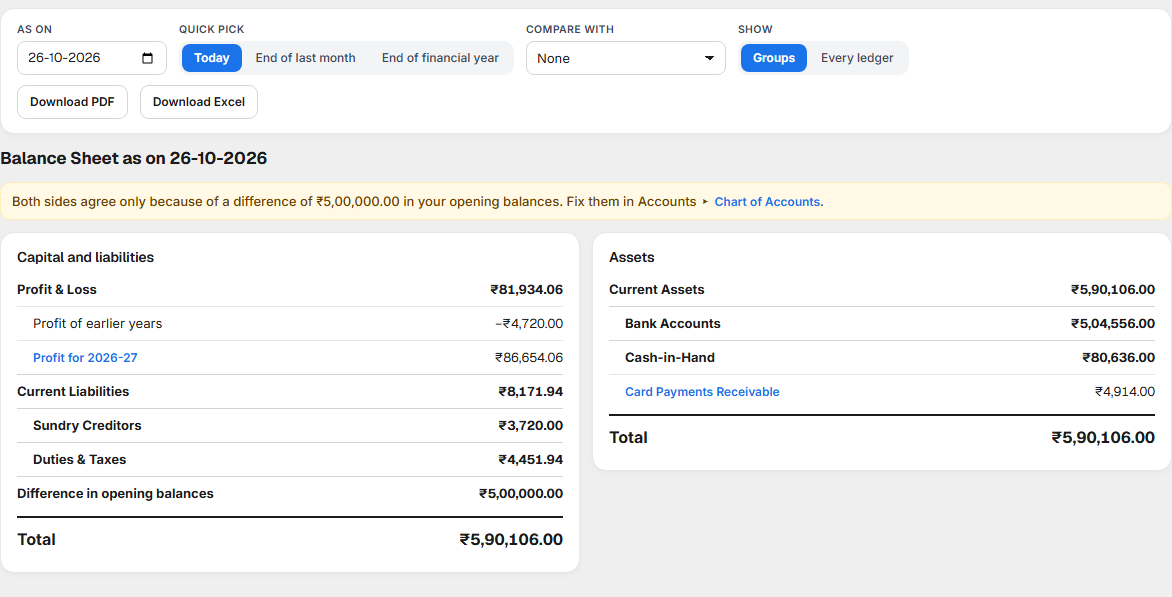
Choose the date with As on, or Today, End of last month or End of financial year.
| Side | What it holds |
|---|---|
| Capital and liabilities | Your capital; Profit & Loss (profit of earlier years and profit of this year so far); loans; what you owe suppliers, GST and TDS to pay, and expenses due. |
| Assets | Kitchen equipment and furniture; closing stock (on 31 March, when entered); bank and cash; deposits and GST you can claim. |
Both sides must have the same total.
| You see | What it means | What to do |
|---|---|---|
| A green Both sides are equal | The books add up. | Nothing. |
| An amber note that both sides agree only because of a difference in your opening balances | The opening balances you entered do not add up. A Difference in opening balances line makes the totals equal. | Correct the opening balances in Accounts ▸ Chart of Accounts. |
| An amber note that the sides differ | Something does not add up. | Check opening balances and ledgers without a group in Chart of Accounts. |
Trial Balance
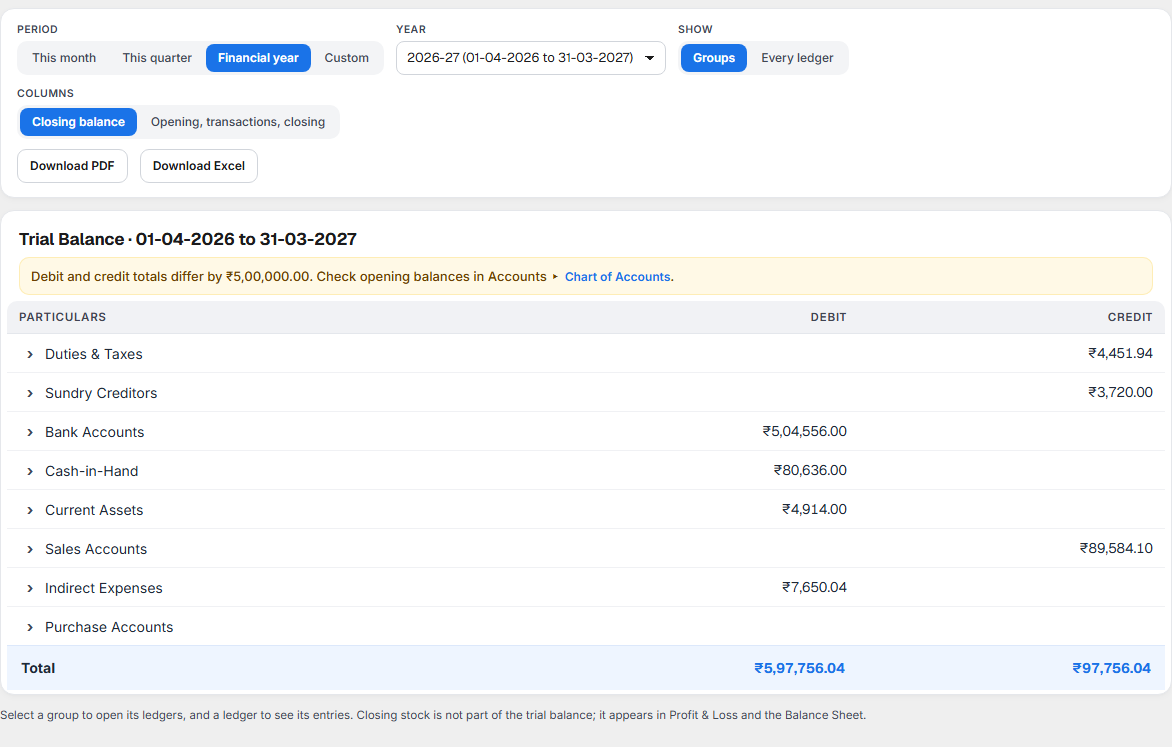
Every group with its balance on the debit or credit side. Select a group to open its ledgers, and a ledger to see its entries. Columns ▸ Opening, transactions, closing adds the opening balance and the debits and credits of the period.
Total debits must equal total credits. When they differ, the amber note gives the difference; the usual cause is opening balances that do not add up. Closing stock is not part of the Trial Balance; it appears in Profit & Loss and the Balance Sheet.
What to check when a figure looks wrong
- The outlet and the period. Every figure is for one outlet and one period. Change either and the numbers change.
- The ledger behind it. Select the line and look at the entries.
- Opening balances. An amber note about opening balances means the starting figures need correcting in Chart of Accounts.
- Days not closed. A sale is in your accounts once the day is closed and the bill is paid. See Day Summary.
Related
- ITR figures — the year's figures for your income tax return.
- Books at a Glance — today's cash, bank and dues.
- Chart of Accounts — ledgers, groups and opening balances.
- Day Book, Ledger and Journals — every entry behind a figure.